Self-service kiosks solve the access problem. But the piece that actually makes them work, day after day, is payment terminal integration, the connection between the kiosk screen, the payment hardware, the processor, the billing system, and the reconciliation report that lands on someone's desk each morning.
This article breaks down what that integration means, how it works step by step, what agencies should require from any provider, and how to evaluate one.
Key Takeaways
- Integration sends amount and account data to the terminal and returns authorization automatically
- A capable kiosk handles cards, contactless, e-wallets, cash, checks, receipts, refunds, and exact change
- PCI DSS, EMV certification, encryption, ADA accessibility, and reliable reconciliation are non-negotiable requirements
- Map integration methods, data needs, maintenance ownership, and total cost before choosing a provider
Payment Terminal Integration for Self-Service Payment Kiosks: What It Means
What Is a Payment Terminal?
A payment terminal is the physical device that captures a card tap, insert, or swipe and returns an approval or decline. It's distinct from the payment gateway (which routes transaction data to financial networks), the processor, and the kiosk software running the customer-facing experience.
The terminal handles the moment of payment. The kiosk application handles everything around it: account selection, amount due, prompts, and receipts, plus the connection back to the agency's billing system.
Integrated, Semi-Integrated, and Standalone Approaches
These architecture terms come from processor documentation, not a separate compliance tier. According to Global Payments and Ingenico:
- Standalone: the terminal has no direct link to the host application; data has to be reconciled separately (Global Payments)
- Semi-integrated: the terminal holds the full payment application and card data goes straight to the processor, while only non-sensitive commands pass to the host (Ingenico)
- Integrated: the kiosk application generates the amount due and controls the full transaction path
For unattended kiosks, semi-integrated or integrated approaches are the better fit. Nobody wants a customer manually keying in a dollar amount at an unattended device.
In a well-built integration, an EMV reader supporting tap, dip, and swipe is tied directly into the kiosk workflow, so the amount moves from account lookup to authorization without re-entry. Integration also does not require ripping out existing systems: terminal connectivity and payment logic can be layered onto a billing environment an agency already runs.

Why Integration Matters in Public-Service Payment Environments
Integration connects directly to outcomes agencies actually care about:
- Fewer keying errors from manual amount entry
- Faster per-transaction times
- Cleaner audit trails for finance teams
- Reduced front-counter workload
- Payment access outside standard business hours
NYC's Department of Finance reported kiosk transactions averaging under one minute, with cash, check, and card acceptance and no added service fees (NYC DOF, 2022). Yuma's utility kiosk runs 24/7/365 with immediate account posting. These are documented municipal examples, not guaranteed universal outcomes, but they show the pattern.
Kiosk-Specific Data Requirements
Unlike a retail terminal processing an anonymous sale, a public-sector kiosk needs to identify which account is being paid. That could mean an invoice number, QR code, barcode, name, account number, property ID, department code, or another custom identifier tied to the agency's own records.
How Payment Terminal Integration Works in a Self-Service Kiosk
The Customer and Account Lookup Stage
The flow starts before payment ever happens. The customer picks a department or service, identifies their account, reviews the balance, and confirms before reaching the payment prompt.
Real-time account validation reduces the risk of a payment landing on the wrong account. File-based or non-validated workflows can still make sense for legacy systems or simpler use cases, but they trade some of that real-time assurance for compatibility.
Passing Transaction Data to the Terminal
Once confirmed, the kiosk sends the terminal:
- The payment amount
- A transaction identifier
- The account reference
- Fee information, if applicable
- Any custom fields (department code, property ID, and so on)
This is where data mapping matters. Every field needs to stay traceable across the kiosk, processor, billing platform, and back-office report. Kiosk Pay Station's approach ties unlimited custom data elements to each transaction, so a department code entered at lookup is still attached when the payment posts to the treasury system.

Authorization, Completion, and Customer Confirmation
The customer taps, inserts, or swipes. The terminal captures EMV or contactless data, encrypts it, and sends it for authorization. The kiosk then needs to clearly communicate:
- Approval or decline
- Receipt options (printed, and digital where supported)
- Canceled or interrupted transactions
- Refund status
None of this should expose sensitive payment details on screen.
Handling Failures and Duplicate Transactions
Unattended hardware fails sometimes. Network timeouts, terminal disconnections, printer jams, and abandoned sessions all happen. Design for those failures up front instead of assuming they will not happen.
Best practice controls include:
- Unique transaction IDs assigned before the terminal is contacted
- Idempotency keys that prevent the same payment from processing twice on retry
- Status checks that confirm final outcome before closing a session
- Exception queues for anything that doesn't resolve cleanly
- Clear on-screen recovery instructions for the customer
Both Stripe and Adyen document idempotency keys as the standard way to let a client retry safely after a timeout (Adyen API idempotency). The same result gets returned instead of a duplicate charge. That logic matters even more on a kiosk with no attendant to catch the problem.

Reconciliation and Reporting After the Transaction
Authorization isn't the same as settlement. An approved payment still needs to flow through settlement, fees, refunds, reversals, and exceptions before it hits daily reconciliation. Automated reconciliation means:
- Traceable records without manual digging
- Cleaner books for finance staff
- Less time spent chasing exception items
- Real visibility into kiosk activity across locations
Essential Requirements for Kiosk Payment Terminal Integration
Payment Methods and Hardware Capabilities
Agencies need to decide upfront what the kiosk must accept: EMV cards, contactless, mobile wallets, cash, checks, and whether exact-change dispensing matters. Pay Station Pro, for instance, accepts cash and checks alongside cards and mobile wallets, with documented cash handling in the $2 to $23,000 range.
Form factor shapes terminal placement, privacy, and maintenance access:
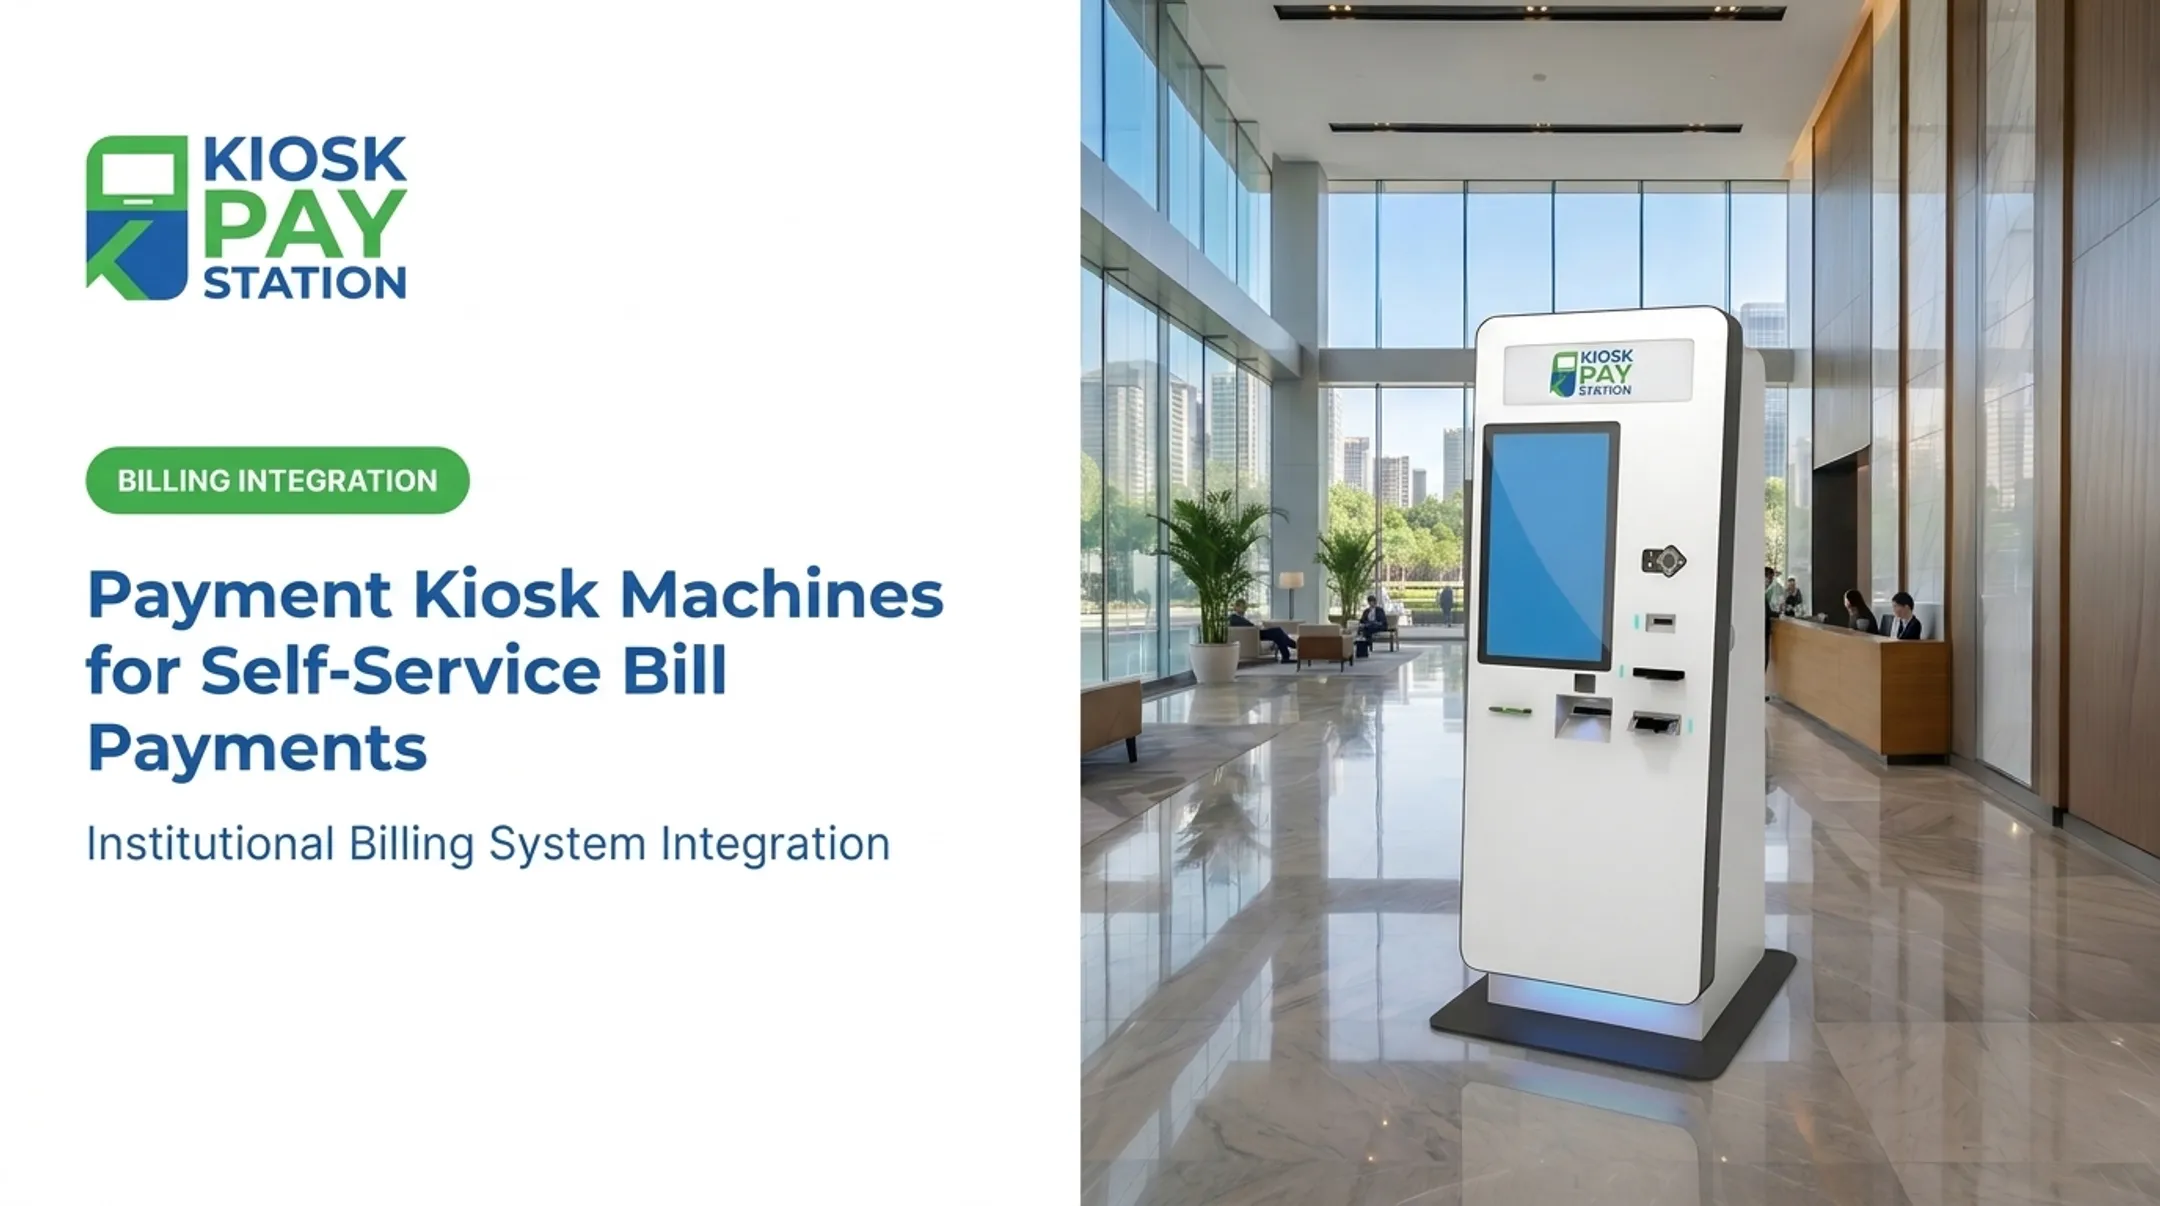
- Standalone — freestanding, suited to high-traffic lobbies
- Countertop — smaller, cashless-focused
- In-wall — recessed, built for permanent exterior placements
Choose the layout that matches lobby traffic, staffing, and service access before you lock in terminal hardware.
Security, PCI DSS, and EMV Controls
PCI DSS v4.0.1 is the current active standard as of December 2024 (PCI SSC). A PCI-approved device alone doesn't make the whole kiosk compliant. Agencies should verify:
- The provider's current certifications and PCI scope
- A clear responsibility matrix for who owns what
- Firmware-update and vulnerability-management processes
- Incident-response obligations
EMVCo separates Level 1 (interface) from Level 2 (kernel/software) certification, and both should be confirmed for the exact terminal deployed (EMVCo).
Avoid storing raw cardholder data. Use tokenization and masking, and log administrative access.
Accessibility and Customer Experience
ADA design standards set specific physical limits: unobstructed reach between 15 and 48 inches, adequate clear floor space, and reachable operable parts (DOJ 2010 ADA Standards). Beyond physical reach, kiosks should offer:
- Multilingual interfaces
- Plain-language prompts and fee disclosures
- Voice or light guidance
- Accessible error messages
- Receipt choices
Reliability, Connectivity, and Monitoring
An offline kiosk that keeps charging cards is a liability. Agencies need a clear policy: what can be safely queued, what must be declined outright, and how payment status gets verified once connectivity returns. Ongoing device-health monitoring and alerts for offline terminals or component failures belong in the baseline requirements.
Cash, Check, and Unattended Kiosk Operations
Cash-capable kiosks carry extra operational weight:
- Bill validators and check readers
- Coin and bill dispensers
- Cashbox access and jam detection
- End-of-day balancing procedures
- Secure collection routines
These require more reconciliation and physical security planning than a card-only terminal.

Scalability and Customization
Agencies with multiple departments or locations need fleet-wide consistency. Centralized reporting, configurable receipts, branded screens, and shared account-lookup rules should work the same on every kiosk, whether the fleet is one unit or twenty.
Planning, Testing, and Choosing an Integration Provider
Discovery and Compatibility Assessment
Before signing anything, document:
- Existing billing or case-management system
- Current payment processor and gateway
- Network and data-field requirements
- Settlement process and receipt requirements
- Accessibility standards that apply
- Internal ownership of support once live
Decide whether you need real-time APIs, file exchanges, non-validated payments, or custom development against existing infrastructure.
Testing, Deployment, and Ongoing Support
Run sandbox and pilot testing across every scenario you will face in production:
- Approved, declined, refunded, and reversed payments
- Timed-out and duplicate transactions
- Cash, check, and card or e-wallet paths
- Accessibility flows your policies require
Then move to phased deployment with staff training, remote monitoring, and a defined escalation path for failures.
Provider Evaluation and Relevant Company Example
Compare providers on the factors that affect live operations, not just the sales demo:
- Certifications and encrypted processing (PCI-DSS, EMV)
- Fit with your terminals, network, and billing stack
- Custom data capture, reconciliation, and reporting
- Real-time, file-based, or non-validated integration options
- Monitoring, maintenance terms, support ownership, and total cost of ownership
Kiosk Pay Station, focused on government and public-service bill-payment integration, is a useful reference for what that checklist looks like in practice:
- PCI-DSS compliant, EMV certified, encrypted processing
- Support for cash, check, credit/debit, and e-wallet payment workflows
- Integration patterns that respect ADA and multilingual interface requirements
- Unlimited custom transaction data (department codes, account numbers, property IDs)
- Real-time, file-based, or non-validated integration options
- Monitoring, maintenance coordination, and ongoing support for live deployments
Riverside County, one of Kiosk Pay Station's customers, reported that two kiosks collected $3.01 million over a seven-day period, more than eight staffed cashier stations processing $2.4 million in the same window. This is a company-reported figure from a specific deployment and time period, not a guaranteed outcome for every agency.

Conclusion
Payment terminal integration is the foundation of any reliable self-service payment workflow. It connects the customer interaction, the authorization, the account posting, the reporting, and the reconciliation that follows.
Before selecting a provider:
- Map your current payment process end to end
- Define security and accessibility requirements clearly
- Test every failure scenario, not just the happy path
- Choose a partner who can support what you need today and what your kiosk fleet needs in five years
Frequently Asked Questions
What are payment processing terminals?
Payment processing terminals are the hardware that capture card or contactless data, send it securely to a processor, and return an approval or decline. They are separate from payment gateways and from the kiosk software that manages the full transaction.
What is the difference between a payment terminal and a payment gateway?
The terminal is the customer-facing hardware that captures the tap, dip, or swipe. The gateway securely routes that transaction data between the kiosk, the processor, and the financial networks behind it.
How does a self-service kiosk connect to a billing or utility system?
The kiosk looks up the account, sends the payment amount, receives authorization, and posts the payment back to the billing system. Connection usually runs through an API, file exchange, or another supported method, then reconciliation closes the loop.
What payment methods should a self-service payment kiosk accept?
Match methods to your constituents and operations. Common needs include EMV cards, contactless, mobile wallets, cash, checks, and exact-change support—though not every agency requires all of them.
Are integrated payment terminals secure and PCI DSS compliant?
Security depends on the full deployment, not the terminal alone. That means certified hardware, encryption, access controls, secure updates, and the agency’s own PCI DSS responsibilities.